• Home
  • About Tracy
  • Contact Me

Using Time Wisely

Organized to save money, energy, and time

  • Email
  • Facebook
  • Pinterest
  • RSS
  • Twitter
  • YouTube
  • Document Organization
    • Overview
    • Box 1
      • Credit Report/Cards
        • Credit Reports
          • Credit Updates
          • Credit Scores
        • Credit Cards
      • Personal
      • Home Ownership
      • Vehicles
    • Box 2
      • Life Insurance
      • Major Medical
      • Tax-Favored Programs
      • Prescriptions
      • Dental & Vision
      • Special Health Policies
      • Short-term Disability
      • Long-term Disability
      • Personal Insurance
    • Box 3
      • Social Security Documents
      • Retirement
      • Investments
      • Estate Planning
      • Tax Records
  • Household
    • Cleaning
    • Maintaining
    • Organizing
    • Scheduling
      • Laundry
  • Event Planning
    • Assisting
    • Attending
    • Coordinating
      • Birthday Party
      • Christmas
      • Dinner Party
      • Fall Festival
      • Field Trip
      • Lemonade Stand
      • Thanksgiving
    • Learning
    • Preparing
    • Serving
  • Miscellaneous
    • Communication
      • Customer Service
      • E-mail
      • RSS Feed Reader
    • Goals
    • Organization
    • Time Management
      • To Do List
  • Food
    • Food Prep
    • Grocery Shopping
      • Lists
      • Pricing
    • Menu Planning
    • Recipes
    • Stockpile
  • Family Activities
    • Going Out
      • Free Outings
      • Inexpensive Outings
      • Summer
    • Rewards
      • Good Grades
      • Reading
      • Summer Reading
    • Staying at Home
  • Stretching Your Dollars
    • Daily Deals
      • Groupon
      • LivingSocial
    • Drugstores
      • CVS
    • Gas Prices
    • Gifts
    • On-line Shopping
    • Pictures
    • Products
    • Restaurants
    • School Items
    • Tips
You are here: Home / Archives for Document Organization / Box 3

Investment: Financial Institutions – Part 3 of 3

March 10, 2013 by Tracy

InvestmentThis past week, I brought file box 1 with me to start going through slot by slot checking that all the information is updated and current. Every time I thought I would get a few minutes to work, I ended up needing to address something else. Therefore, I will try again this coming week. 😉

If you are struggling finding time to organize your important documents, take a deep breath as this is a marathon, not a sprint. Keep this task on your radar.

Find a time that works for you. For me, I already spend time twice a month working to pay our bills, file documents, etc. During those times, I work on our important documents.

Just find what works for you. Don’t worry about the past. Just focus on what you can do this week.

Within our investment category, we have looked at U.S. Treasury Savings Bonds, cash accounts, documents for adult accounts, and documents for children’s accounts. For each of our cash accounts, we have a beneficiary designation form on file. Though each financial organization has their own process, of which you might need to ask, designating a beneficiary for each of your accounts protects your investment.

Part 3: Beneficiary Designations

Financial Institution #1

At our preferred financial institution, we designated our beneficiaries when we opened our accounts. The Payable-On-Death Account (POD) In Equal Shares form required the following information:

      • Account number
      • Account Suffix(es) – checking and savings
      • Account owner’s name
      • Account owner’s social security number
      • Primary beneficiary’s name, address, date of birth, social security number, and percentage of beneficiary (You can choose multiple primary beneficiaries, but the total must equal 100%.)
      • Contingent beneficiary’s name, address, date of birth, social security number, and percentage of beneficiary (You can also have multiple contingents – payable only if there is no surviving primary, but the total of the percentages must equal 100%.)
      • Signatures of all account holders

Upon setting up our estate planning documents, I submitted new Payable-On-Death Account (POD) In Equal Shares forms for each of our accounts to keep all the primary and contingent beneficiaries the same.

I keep a copy of those forms for verification. Also, I confirm our current designations annually by making a call and checking on each of our 5 accounts.

Financial Institution #2

For our second financial institution, we had to ask for beneficiary designation information. We were directed to the branch manager to get the proper Payable On Death Agreement which required the following details:

      • Account number
      • Account owner’s name and signature
      • Joint owner(s) name(s) and signature(s)
      • Primary beneficiary’s name, relationship to account holder, address, date of birth, social security number, and telephone number (For this institution, they do not usually authorize contingent beneficiaries. However, I adjusted the form indicating primary and contingent beneficiaries.)

Though I have not changed our beneficiary designations with our second financial institution, I still check annually to confirm that our designations have not been altered.

To protect our investments, we establish beneficiary designations on each of our accounts. Though some institutions automatically setup beneficiaries, you may need to research and ask for your designations.

As you organize your important documents, check for beneficiary designations for your investments. If you don’t find any, then contact your financial institution to inquire about their policy and how to designate your beneficiaries.

You have safeguarded your investments within your financial institution, so make sure those investments are there when you are no longer available. Happy designating!

Question: How does your financial institution handle beneficiary designations?
Filed Under: Box 3, Investments, Document Organization Tagged With: Investment

Investment: Paid-in-full Loan Documents

March 17, 2013 by Tracy

InvestmentIn our File Box 3, we have filed our Social Security documents and retirement documents.

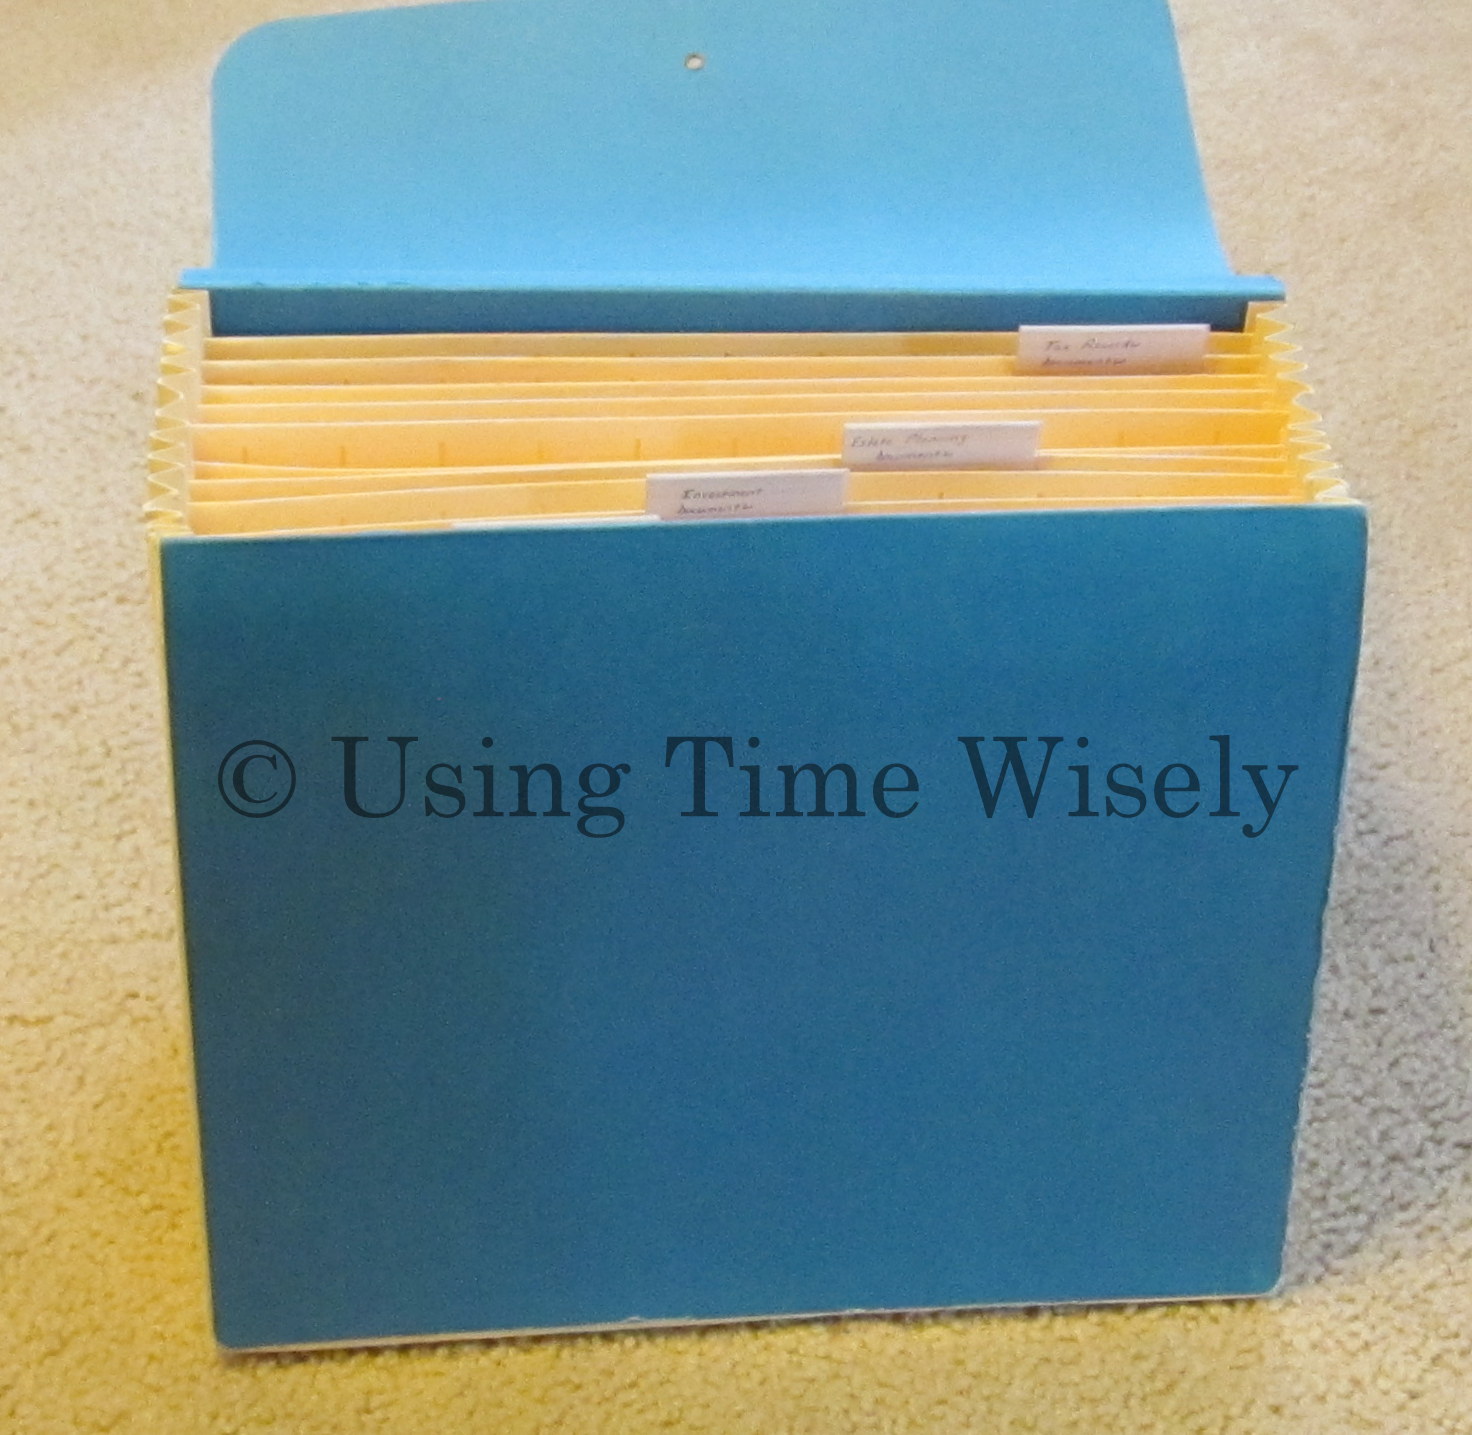
The third category holds our investment documents housed in file slots four and five of our accordion filing system.

With our U.S. Treasury Savings Bonds, cash accounts, financial accounts for adults, financial accounts for children, and beneficiary designations filed in slot four, I turn to the first set of paperwork placed in the fifth opening – our paid-in-full loan documents.

Paid-in-full Loan Documents

This post is not to address whether or not one should take out a loan. Doing what is best for your family may look different from your ideal.

If you have never taken out a loan, then you can skip this section. Paul and I both had loans which we paid back and keep the records within our filing system.

Education Loans

Paul and I both had education loans. I carried my loans into our marriage from my undergraduate degree as I did not incur any additional loans from my graduate work. Once those two promissory notes were paid, we kept the paid receipts received from the providers.

When Paul needed additional education, we took out a loan with an interest-free payment plan. In paying off the loan early, we did not incur any interest charges. We keep the documents associated with this loan in our file as long as the record remains in our credit file.

Personal Loans

Coming into our marriage, Paul and I both had a personal loan. My grandmother sold me a vehicle when I was in school which I did not need to repay until after college. I began paying her back without interest when I graduated until we paid it in full.

I kept her handwritten receipt. I’m so thankful for this note as my grandmother passed away a little over a year ago. I know I have her handwriting in cards, but this note was an official receipt showcasing her beautiful handwriting.

Paul’s personal loan was from his parents for my engagement and wedding rings which we paid back in one lump sum.

Though I do not need to keep these two personal loan documents, I do. They remind me of our hard work in focusing on our debt and paying back what we borrowed. I still remember the great feeling when we wrote those last checks and became debt free.

Keeping these documents in the order in which we paid, I paperclip them together and place them in the fifth file opening under the third category of investment documents. When money gets tight, I enjoy looking at these documents as a reminder of how God provided during our very lean years.

Weekly Project: Locate and file your paid-in-full loan documents.

Next week, we will complete the investment documents category with closed bank account letters. Keep making progress as you create spaces for your important documents. May you find encouragement as you file your paid-in-full loan documents. Happy organizing!

Question: Do you find encouragement from looking at your paid-in-full loan paperwork?

Filed Under: Box 3, Investments, Document Organization Tagged With: Investment

Investment: Closed Bank Account Letters

March 24, 2013 by Tracy

InvestmentFor only having 5 categories in File Box 3, I feel like it is taking so long to progress through this file box which is partly due to the interruptions in December and January. In spite of the delays, we will complete the investment documents category today. 🙂

The following is a recap of the documents housed within the two file openings of our accordion filing box holding our investment documents:

Fourth File Slot

  • U.S. Treasury Savings Bonds
  • Cash accounts – with free printable record
  • Financial accounts for adults
  • Financial accounts for children
  • Beneficiary designations

Fifth File Slot

  • Paid-in-full loan documents
  • Closed bank account letters

Closed Bank Account Letters

When I was organizing our important documents, this category never crossed my mind. In her Protection Portfolio, Suze Orman designates a slot for closed bank accounts.

In thinking through all the financial institutions where I held accounts, I had assumed the accounts were closed when I withdrew all the money. However, I did not have letters confirming those accounts were closed.

Requesting Closed Bank Account Letters

This process took some time as I contacted each financial institution for both Paul and I. Together we had 8 accounts with some of them banks and others credit unions. Then I took the following steps:

1. Located the account numbers for each financial institution (e.g., consulted checks, bank statements, and correspondence),

2. Contacted each financial institution,

3. Verified that our account was closed,

4. Requested a letter stating the account was closed by consumer,

5. Received the letter via mail, fax, or e-mail, and

6. Filed the closed bank account letters within our file box 3.

Obstacles Gaining Closed Bank Account Letters

Though it sounds easy to just contact the company, I did run into these obstacles along way:

1. Account information had been purged from the financial institution

After a few rounds of trying to get a letter, I finally spoke to a vice president at the main branch who sent a letter stating that we no longer had any open accounts and included our social security numbers as the account numbers could not be verified.

2. Needed our request in writing

Upon calling some of our financial institutions, they required our request in writing. I composed a letter and mailed it to the bank or credit union. I chose not to fax as our social security numbers were on the document, and I did not know who had access to the fax machine.

FREEBIE: Should you need to provide a written request, you may use the following sample letter to make your inquiry:

Free printable Bank Account Closing Letter – WORD document format

3. Financial institution had a merger after the account was closed

For these accounts, the current financial institution did not have records from the previous bank. So, they provided a letter indicating the original account numbers from the previous bank and the new account numbers had been closed and, in one case, purged from their system.

4. No records found for the account numbers

One institution could not find any information, so they provided a letter stating that they were unable to locate any records.

Having the verification that all non-used accounts are closed, we know where our money rests. We also have confirmation that our other accounts are closed should an unauthorized transaction take place. The letters provide proof that the financial institution closed our account or has no open accounts with our names or social security numbers.

Weekly Project: Gather your closed bank account letters or contact financial institutions to receive closed bank account letters.

In organizing your important documents, you might find this step time-consuming. As I did not have any of these letters when I started organizing my file, I invested my time calling and writing to get this information. Now, I know that all our accounts are current with no outstanding fees or monies at other banks or credit unions.

This post brings our third category to a close. You have some time to work on this step as I will begin the fourth category in May. For April, I will try another month of themed posts. Look for more details in this Wednesday’s post.

Keep making progress. In using time wisely, your investment of time and energy will let you know exactly where your investments lie. Little by little your filing system is coming together. You are in the homestretch with only two more categories to go. Happy organizing!

Question: Do you typically request a closed bank account letter when changing financial institutions?

Filed Under: Investments, Box 3, Document Organization Tagged With: Investment

Estate Planning Documents Overview

May 5, 2013 by Tracy

InvestmentWe have reached my favorite section of our important document organization – the estate planning documents. This is actually the section where I disagree with Suze Orman.

She is a financial planner, and I appreciate her financial advice. However, estate planning is legal based, and Suze, Love Bug, is not an attorney.

Having worked in the legal field as a legal secretary and then a legal assistant, I learned the value of a great attorney. For our estate planning documents, we hired an attorney. When we purchased our estate planning package, we paid around $600 almost 10 years ago which was worth every cent.

Before we dive into the estate planning section, let me give you a quick review of how far we’ve come, and an overview of where we are going.

Review

For those of you just joining our document organization or those who just need a reminder, we have organized File Box 1 and File Box 2. We are plugging away at the 5 sections of File Box 3. Having covered our Social Security documents, retirement plan documents, and investment documents, let’s turn to estate planning documents.

Overview

Located within 5 file openings, I keep the following documents in our Estate Planning section:

    • File Opening 1: Checklists
    • File Opening 2: Estate Planning Documents
    • File Opening 3: Copies of Estate Planning Documents
    • File Opening 4: Correspondence
    • File Opening 5: Research

As we cover the contents of each file opening, I will share the choices Paul and I have made. Our situation is different from yours, and a reputable, local attorney can best advise you on your state’s laws and your estate planning options.

If you purchased a Suze Orman Protection Portfolio, please do not use her estate planning documents. The only exception would be if you live in California, but even then, you would want to hire a local attorney to review the documents for you.

Creating these estate planning documents is too important to go the easy, cheap route. You definitely need experience when putting your house in order.

Please do not ignore this section because you do not have $600 to fork over to an attorney. Paul and I saved for almost 2 years before taking the plunge. Knowing what you need and what documents the attorney needs will empower and give you confidence when you seek an attorney.

Next week, we will begin the checklist section of our estate planning documents. Feel free to ask any questions. I will do my best to point you in the right direction, but I am not a legal expert or an attorney. Happy organizing!

Question: How much did you pay for your estate planning documents?

Filed Under: Box 3, Estate Planning, Document Organization Tagged With: File Box 3

Estate Planning: What To Do When Someone Dies Checklist

May 12, 2013 by Tracy

Estate PlanningLast week, we started with an overview of the estate planning category. This category takes up 5 file slots in my File Box 3. The first file slot contains checklists. The first type I keep is the What To Do When Someone Dies checklist.

Thinking about someone close to you passing away is tough. I do not want to think about what would happen should Paul pass away. However, should that happen, I will be a mess.

My emotions will get the better of me, and I will not be able to think. So, I need to prepare BEFORE something happens, so I can just follow the instructions.

I know I won’t be alone, but I will know where all the documents are and whom we have partnered with for our financial, insurance, and medical well-being. Having a checklist to follow will focus my brain on completing the next step without trying to figure out where to start.

WARNING: Before I share some resources that I find helpful, I want to preface this information with a warning that these checklists are for informational purposes.

Should Paul pass away, one of my first calls will be to our attorney. I will confirm with him the order in which I need to proceed per our state’s laws. Having a legal partner is the key to completing this process thoroughly, completely, and legally.

What To Do When Someone Dies Checklist

The following checklists offer anywhere from basic to extremely detailed instructions. Personally, I like to know all the information.

However, I keep simple and detailed checklists in my estate planning file slot because I may need something really simple in the first days just to get through the initial shock. Keeping a couple checklists will give you options should a loved one pass away.

Simple Checklists

    • The Consumer Reports checklist is organized by time frame – immediately, within a few days, and up to 10 days.
    • Created by Barbara Repa, a California estate planning attorney, this checklist, with boxes to mark off the items, gives practical advice based on the following time frames – within the first hours, within the first day, and within the first days to weeks.
    • Designed by an attorney and his wife, who are caregivers, this printable checklist allows you to mark off the items as you complete them. If you are a caregiver or have aging parents or grandparents, then you might want to keep this checklist handy.

Detailed Checklists

    • Prepared by Virginia attorney, Dan Newland, this checklist provides 34 items in a sequential numbered format. 
    • Specifically designed for California residents, this checklist includes boxes to check off as you complete each item.
    • My favorite is this thorough 16-page printable checklist with explanations and an area to mark off completed tasks from Colorado attorney Gary Johnson.

In keeping a printout of two or more checklists, you will have a starting point should you find yourself asking, “What to do when someone dies?” Though I don’t like to dwell on what could happen, I prepare should the worst take place. I do not take out these checklists to read them, but I keep them filed – just in case.

Weekly Project: Print one or more What To Do When Someone Dies checklist and file within your estate planning category.

One benefit to having these checklists is learning some tangible ways to help those who lose a loved one. I have stayed at homes twice during a funeral to distract any thieves, who prey on families during their time of grief.

Next week, we will continue with another checklist that I keep filed within our estate planning documents. Getting your important documents organized will make retrieving those documents quick and efficient when you need them.

The process takes lots of time and energy, but in using time wisely, you will save time in the long run. Happy organizing!

Question: Do you prefer a simple checklist or a detailed fully-explained checklist?

Filed Under: Box 3, Estate Planning, Document Organization Tagged With: checklist, Estate planning

« Previous Page
Next Page »

Welcome to Using Time Wisely!


Presenting organizational tips and tricks to save you money, energy, and time. Enjoy the journey of Using Time Wisely.

Looking for something?

Copyright © 2026 · Lifestyle Pro Theme on Genesis Framework · WordPress · Log in